
YOUR BUSINESS ALLY
Guide to Buying and Selling a Family Business in Alberta
Do you have concerns about how you'll pass your family business to the next generation?
Careful planning will help protect both the business and your familiy.
- Business Transition Basics
- Preparing For a Sale or Purchase
- Developing Your Plan
- Tax Implications
- Financing the Transaction
- Zenally's Role in Transitions
Trust makes family deals flexible. Paperwork keeps them friendly.
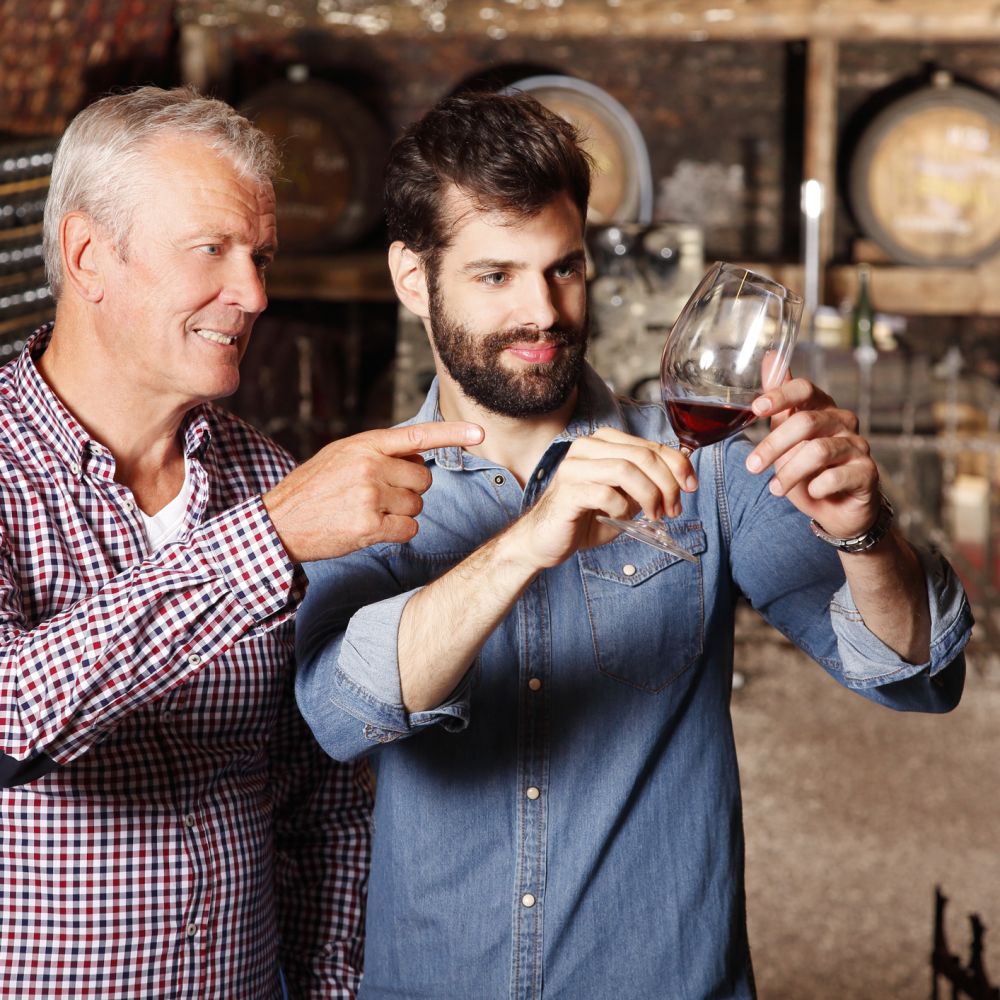
When buying or selling a business within your family, things can get tricky. It's not just about the money; it's about maintaining relationships too.
That's why it's so important to manage expectations around family business transactions right from the start.
The Meeting: Legacy of the Vine
As Kelly neared retirement, he was keen to pass his successful winery to his son, Jason. He had no doubts about it, but was aware of the challenges Jason might face stepping into his role.
Kelly, seasoned and prudent, wanted to be sure the winery had sound leadership before stepping back. He valued stability and tradition, which had been the backbone of their success.
Jason, on the other hand, brimmed with new ideas and a desire to innovate, occasionally clashing with his father's more conservative approach. Bridging these generational perspectives was a necessary first step for a harmonious transition and the continued prosperity of the winery.
I was privileged to help them navigate this pivotal transition. We started with a comprehensive valuation, blending income and market-based analyses to determine the winery's value and growth potential. Financial details were complex, with capital gains taxes a major concern. Together, we strategized to minimize tax impacts, preserving the financial health of both the brewery and the family.
Financing the transfer was the biggest challenge.
Understanding the pressures Jason would face, Kelly opted for seller financing. This approach allowed Jason to take over without financial stress, and provided Kelly with a steady retirement income.
Recognizing Jason's upcoming challenges, I facilitated several meetings to align his visions with the established business. Passionate yet inexperienced, Jason faced the daunting task of upholding the brewery's reputation while infusing his innovative ideas. He proposed introducing new blended wine flavors, eager to attract a younger clientele without alienating the brewery's loyal customers.
The outcome was a carefully crafted agreement that balanced Kelly's rich legacy with Jason's modern approach. This collaborative strategy prevented potential conflicts and supported Jason as he navigated his new responsibilities.
Kelly now enjoys retirement, content in seeing Jason blend tradition with innovation. He occasionally visits the winery, enjoying both the past and the vibrant future Jason is building.
Together, they share stories and successes, a testament to a well-planned transition that honors both their dreams.
Understanding the Basics of Family Business Transitions
A family business transition involves buying or selling a business to someone within your family, like a parent, sibling, or cousin. It's different from selling to a stranger. With family, you have a shared history and, likely, a future together beyond the business. Depending on the family dynamics, this can make negotiations smoother or more complicated.
Every decision you make affects both the business and your family relationships.
It's super important to be clear and open from the start. Transparency helps everyone involved understand the process and avoid misunderstandings.
In the following sections, we'll explore how you can prepare for these transactions, manage taxes, and handle financing. We'll also discuss how a Zenally CPA can be your best ally in ensuring smooth operations. So, let's get started and be sure you're set up for success in your family and business!
Preparing for a Sale or Purchase
You don't get ready to buy or sell a business to a family member on a whim. It requires careful planning and preparation to ensure everything goes smoothly and everyone is satisfied.
Valuing the Business
First, you must know what the business is worth. This isn't just about the numbers on the balance sheets; it's about understanding the actual market value of what's being bought or sold. An accurate valuation is important, especially in family transactions, to avoid feelings of unfairness or regret later on.
You can use several methods to value the business, like looking at the revenue and profits or comparing it to similar businesses for sale. Zenally can help break down these methods and choose one that best suits your situation.
Legal Considerations
You need to dot the 'i's and cross the 't's.
You'll need all the necessary legal documents, such as purchase agreements, contracts, and any other paperwork required by law. These documents should clearly state the terms of the sale, including payment plans, the responsibilities of each party, and what happens if someone backs out. Getting a lawyer involved is an excellent idea to ensure everything is legally buttoned up.
In family deals, it's also wise to draft an explicit agreement that outlines each party's expectations and obligations. This agreement can help prevent misunderstandings and ensure everyone is on the same page, protecting business and family relationships.
Tax Implications
When buying or selling a family business in Alberta, the tax side of things can get complex. But don't worry; understanding these implications upfront can save you a lot of headaches (and money) down the road.
Capital Gains Tax
When you sell a business in Canada, you might have to pay capital gains tax on your profit. The good news? You can claim the Lifetime Capital Gains Exemption (LCGE) if your company qualifies as a Small Business Corporation.
(In Budget 2024, the Federal Government announced changes to Capital Gains Exemptions. Stay tuned to our blog for updates.)
Excluding Assets from the Sale
Before transferring the business, assessing and possibly selling certain assets is wise. Alternatively, consider selling only the business and leasing the property it inhabits to the new owners.
These strategies can help reduce the price of the business, making it financially more accessible to family members.
Tax Strategies for Family Transfers
Tax strategies like income splitting or staggered selling can benefit family business transactions. For example, suppose the business is sold in parts over several years. In that case, it might reduce the overall tax burden by keeping you in a lower tax bracket each year.
Another strategy is to structure the transaction as a loan to the family member, which can be repaid over time, potentially offering tax advantages.
Getting Professional Help
The intricacies of tax law make consulting with a Zenally CPA advisable. We can offer personalized advice and ensure that your family business transaction is as tax-efficient as possible. We'll strive to protect both your financial interests and family relationships.
Financing the Transaction
Sorting out the finances when buying or selling a business within the family is a balancing act. You want to keep things fair and professional. Still, you also have the advantage of trust and familiarity, which opens up some flexible financing options that might not be advisable with outside buyers.
Traditional Financing Options
Even though you're dealing with family, you can still use conventional financing methods. This could mean taking a business loan from a bank or other financial institution. These loans are generally offered with standard terms based on creditworthiness and the business's financial health. It's pretty straightforward, but involving a bank means there will be interest rates and repayment schedules to consider.
Seller Financing
This is where things can get a bit more tailored. Seller financing happens when the person selling the business also acts as the lender. For example, if you're buying your sister's share of the business, she could agree to let you pay her over time instead of all upfront.
This method can make the transition smoother and sometimes avoids the hassle of bank approvals. Plus, it keeps the financial dealings within the family, which might be easier for everyone involved.
Gift or Partial Gift Transactions
Sometimes parts of the business might be gifted, especially if parents pass down their life's work to their children. This approach can reduce financial strain on the buyer, but remember, as we mentioned earlier, this could have tax implications.
Creating a Payment Plan
Another option is to set up a payment plan that suits both parties. This can be especially helpful if the buyer (maybe you or another family member) doesn't have the total amount upfront. A well-documented payment plan can keep things clear and prevent any misunderstandings in the future.
The Importance of Clear Agreements
No matter which financing option you choose, the key is to have everything clearly written down in an agreement. This helps ensure that everyone knows what to expect and can help avoid any potential disputes.
Zenally's Role in Family Business Transitions
When buying or selling a family business, having Zenally by your side is more than just a smart move - it's important for smoothing out the financial and emotional wrinkles that can pop up.
Facilitating Fair Valuations
Determining the fair market value of a business is one of the first steps in any sale, and it can get tricky, especially with family emotions involved. We bring a level of objectivity and expertise to the table. We use established methods to calculate a fair price, ensuring all parties feel the valuation is just and transparent.
Navigating Tax Waters
As discussed earlier, the tax implications of buying or selling a family business can be complex. Zenally can guide you through this maze, helping you take advantage of tax benefits and avoid pitfalls. We ensure that all tax filings are accurate and compliant with regulations, which can save you a significant amount in unnecessary tax payments.
Structuring the Deal
Every family and business is unique, and our CPAs can tailor the transaction structure to best suit your specific needs. Whether it's seller financing, a staggered sale to ease tax burdens, or setting up trusts and estates for long-term planning, we can provide the necessary expertise to set up a structure that benefits everyone.
Ensuring Compliance and Documentation
Any major business transaction involves a lot of paperwork. Zenally ensures that every document, from contracts and agreements to transfers of ownership and loan documents, is in order, legally compliant, and filed correctly. This meticulous attention to detail helps prevent any legal or financial issues.
Providing Peace of Mind
One of the most significant benefits of having a CPA help with your family business transaction is the peace of mind it brings. Knowing an expert is handling the financial details allows you to focus more on the relational aspects of the transition—maintaining and nurturing family ties during and after the sale.So, whether you're stepping into a new role in a family business or passing your legacy down to the next generation, Zenally can be your best ally. We keep the process running smoothly and help preserve the family bond that's so important to you.
Buying or selling a family business in Alberta involves more than just crunching numbers and signing papers. It's about preserving relationships and ensuring a legacy that can continue to thrive under new management. Throughout this process, it's essential to handle every step with care and professionalism to maintain trust and respect among family members.
Our experienced accountants are here to guide you through every aspect of the transaction - from valuation and tax planning to legal paperwork and financing options.
Are you considering buying or selling your business to family members? Don't navigate this significant life event alone.
We make sure your family business transition is handled with the expertise and sensitivity it deserves.
Business and Tax Advice
for Alberta's small business owners
from Albertan small business owners
Your Business Ally
Phil Cruickshank
Phil is a Partner at the business accounting firm of Zenally Chartered Professional Accountants LLP.
For more than 30 years, he has sat face-to-face with owners of businesses of all sizes. He has listened to them, helped them identify their issues, and provided guidance.
Business owners have left with answers to their questions, less stress moving forward, and confidence that they have a business ally to call on anytime they need.
Interested in finding out more about Phil, his team and what they can do for your business? Contact us.
ZENALLY
Chartered Professional Accountants LLP
Send Us a Message
Payments
Please send eTransfers to
etransfer@zenally.cpa
 Map Link
All personal customer and business information submitted through this website will be held confidential - Privacy Policy
ZENALLY
Chartered Professional Accountants LLP
Copyright 2026 All Rights Reserved
DISCLAIMER: Any accounting, business, or tax advice contained on this website is not intended as a thorough, in-depth analysis of specific issues, nor a substitute for a formal opinion.
If you are interested in talking more about any topic on our website or specifically how the information would likely impact you, we'd be happy to chat.